Research · 16 September 2026 · 9 min read
Four Weeks After the Rally: What 19 August Changed for metaDEX Voters
On 19th August the majors ripped, and vote-escrow DEXes had the best day they had seen in months.
Our assumption going in was simple. When asset values move, trading picks up, and the venues that pay their holders out of trading fees should feel it first. We also thought the effect would be bigger than the extra volume alone, because a repricing day pushes flow out of stable pools charging a few basis points and into volatile pools charging a lot more. Four epochs have now closed, so we can check both.
The week after the market rallied was the second-biggest Aerodrome has ever recorded following a big day, the step up has held for three epochs at about half again the level of the summer before it, and the pool mix argument held too. It has been a good month for metaDEXs, in a difficult year.
The day itself
Against each venue's own trailing seven-day mean, 19 August printed two to five times more.
| venue | fees to voters, wk 13-19 Aug | previous week | change | 19 Aug | mean 12-18 Aug | day multiple |
|---|---|---|---|---|---|---|
| Aerodrome | $811,476 | $704,603 | +15% | $265,696 | $101,760 | 2.61× |
| up (Robinhood) | $180,070 | $181,477 | −1% | $18,138 | $28,448 | 0.64× |
| Nest | $66,752 | $38,036 | +75% | $29,918 | $6,222 | 4.81× |
| Velodrome | $48,492 | $55,534 | −13% | $17,637 | $6,043 | 2.92× |
| Thena | $15,089 | $20,389 | −26% | $4,450 | $1,785 | 2.49× |
| Kittenswap | $7,505 | $6,797 | +10% | $1,960 | $959 | 2.04× |
But, read the week column, which is the one a voter actually gets paid on, and three of the six venues paid out less than the week before. Velodrome had a bigger day than Aerodrome, 2.92× against 2.61×, and still finished the epoch 13% down, because the days either side of it were weaker than the ones they replaced. Volatility has been compressed over the past months, and the breakout has been sandwiched by a compressed market.
The week after
The answer, when it came, was emphatic.
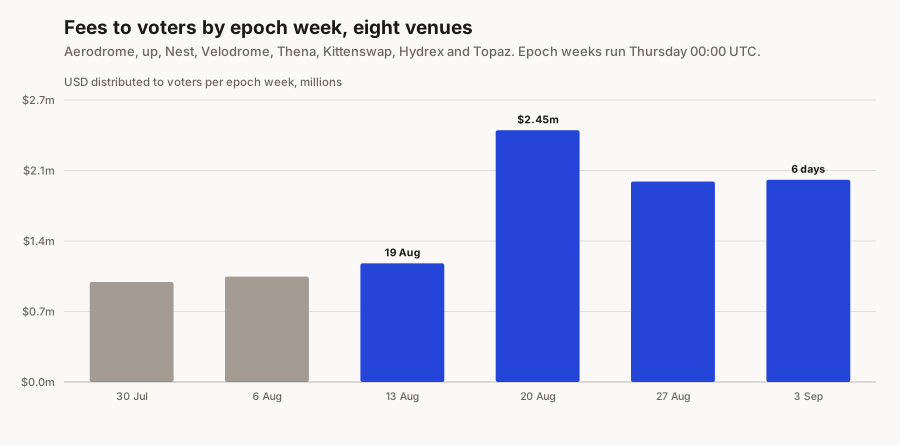
| epoch beginning | Aerodrome | sector total |
|---|---|---|
| 30 July | $784,748 | $972,577 |
| 6 August | $704,603 | $1,025,976 |
| 13 August (contains 19 Aug) | $811,476 | $1,155,381 |
| 20 August | $1,834,597 | $2,450,822 |
| 27 August | $1,133,337 | $1,951,927 |
| 3 September (six days) | $1,211,180 | $1,968,002 |
The 3 September epoch is six days, not seven. DefiLlama first reported Aerodrome's 9 September at about $440,000 and later restated it to $7,922,809, roughly thirty times either neighbouring day, on a volume that was ordinary. That is not a day of trading fees reaching voters, so the day is dropped rather than guessed at, and every figure below that spans it says so. The excluded value is recorded in the data sources file that the pull regenerates.
Aerodrome's epoch beginning 20 August paid out $1,834,597, up 126% on the week of the rally itself.
So we looked at what usually happens. Aerodrome has had 86 days where fees to voters came in at double the previous week's daily average or more. Each time, we checked what the next epoch paid. It was up 47 times out of 86, near enough a coin flip, and the median gain was 3%. A big day normally tells you nothing about the next epoch. The week of 20 August was the exception. At +126% it ranks second of all 86.
A couple of obvious conclusions:
- A big day does not necessarily tell you if that epoch will be particularly good.
- A day this big, might. We've only seen an event this big a few times in the past 3 years.
So, did it hold?
Three epochs later, yes. It would seem that the market moved significantly, to the benefit of metaDEX users, paying out about half again what an epoch did before.
Aerodrome's three epochs after the rally averaged $1,393,038, against $960,981 across the nine before it, back to the second week of June. That is 1.45×. The two epochs immediately before the rally were the quietest of the summer, so measuring against them alone would flatter the step up; the nine-epoch baseline is the fairer one. The sector total moved the same way: about $1.0m to $1.2m an epoch in the three weeks before, about $1.9m to $2.5m in the three since.
The check worth running is each epoch's payout against the locked value in the same week, because both sides are measured in dollars. If the improvement were only the AERO price going up, the locked value would rise with it and the ratio would stay flat. It did not.
| epoch | fees to voters | locked value, that week's snapshot | epoch against locked |
|---|---|---|---|
| 13 August | $811,476 | $472.1m | 0.172% |
| 20 August | $1,834,597 | $538.8m | 0.340% |
| 27 August | $1,133,337 | $506.1m | 0.224% |
| 3 September (six days) | $1,211,180 | $578.2m | 0.209% |
Across the twelve weeks before the rally that ratio ran between 0.149% and 0.302%. The week of 20 August cleared the top of that range outright, and the two epochs since have settled back inside it, near its midpoint, with the six-day epoch understating its own ratio by about a seventh. So the rally did reach voters. It just took a week to show up.
The mechanism held
The second half of our thesis was that a rally pays these venues twice: once for the extra volume, and again for pushing that volume out of the cheap stable pools into the expensive volatile ones. The test is whether fees as a share of volume, the take rate, stays up once the rally stops.
| venue | 9 weeks before | week of the rally | 3 weeks after | change |
|---|---|---|---|---|
| Aerodrome | 5.36bp | 4.67bp | 6.17bp | +15% |
| Nest | 7.70bp | 8.82bp | 11.45bp | +49% |
| Kittenswap | 8.56bp | 9.04bp | 9.98bp | +17% |
| Velodrome | 7.08bp | 5.71bp | 6.58bp | −7% |
| Thena | 16.55bp | 15.64bp | 14.94bp | −10% |
It held where the pool mix argument said it would. Aerodrome's most recent epoch ran at 6.72bp, the highest take rate in the thirteen weeks we looked at. Nest expanded by half.
Two venues went the other way, and we would not read much into either. Velodrome is merging into Aerodrome under the Aero consolidation, so it is not really an independent venue any more. Thena is small enough that one or two pools move its whole number. Where the rotation into higher-fee pools happened it stuck, and where it did not, there was nothing to stick.
up is left out of that table. Its take rate reads 43bp before and 23bp after, an order of magnitude above everything else here, which tells you about the composition of a venue four weeks into life rather than about pool mix. Its payouts ran $170k, $568k and $441k across the three epochs after the rally against roughly $38,000 a week in July, a ramp that started before 19 August and clearly has its own cause.
What did not change
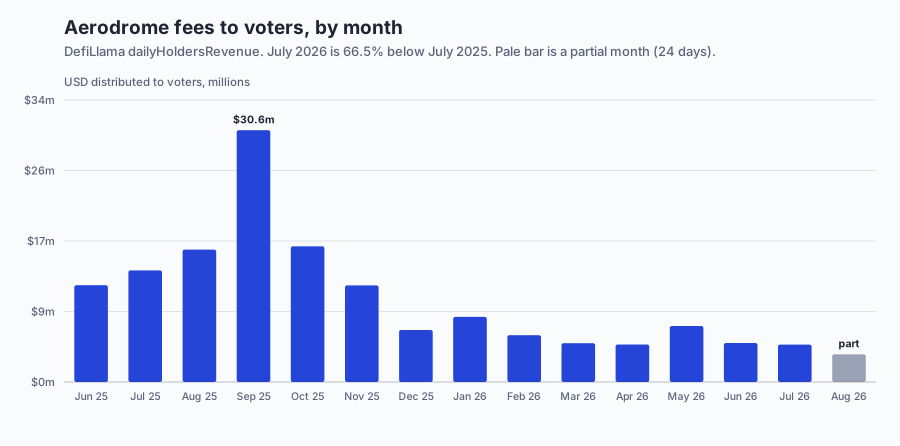
Every figure above is a weekly figure. Step back to months and the picture is almost inert.
| month | fees to voters |
|---|---|
| March 2026 | $4.71m |
| April 2026 | $4.56m |
| May 2026 | $6.80m |
| June 2026 | $4.74m |
| July 2026 | $4.54m |
| August 2026 | $4.67m |
| September 2026 (to 16 Sep, partial) | $3.21m |
August 2026 contained the biggest post-rally week in two and a half years. It finished at $4.67m. July was $4.54m and June was $4.74m. The month of the rally landed 2.8% above the month before it and 1.4% below the month before that.
September is running at about $6.41m on a 30-day pace, which is the top of the band and still short of May. Set against August 2025's $16.09m, or September 2025's $30.60m, the whole episode is a fluctuation inside a level that has fallen roughly 71% year on year.
Both readings are correct, and holding them together is the actual finding. A locked position got paid roughly half again as much, three epochs running, and that is real at the frequency a voter is actually paid. It has not been big enough or long enough to lift the venue off the floor it has sat on since March.
The venue tokens, then and since
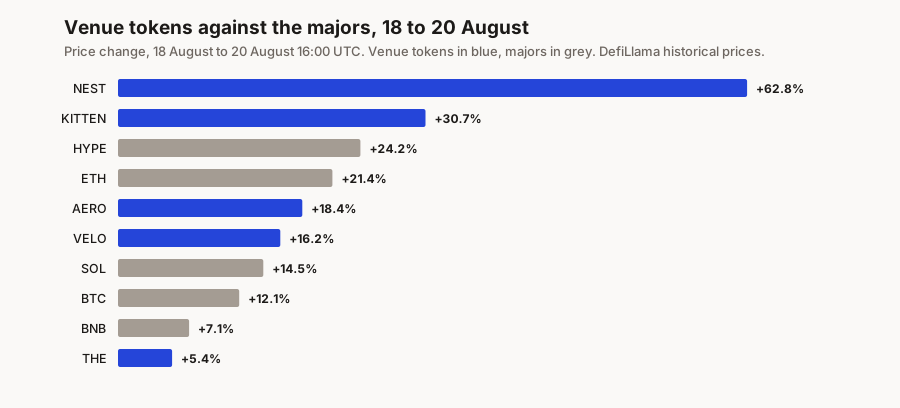
We have kept the original window closed at 18 to 20 August, 16:00 UTC. That window is the rally itself, and stretching it to now would quietly turn a measurement into a trend.
| token | 18 to 20 Aug, 16:00 UTC | 20 Aug to 10 Sep, Radar snapshots |
|---|---|---|
| NEST | +62.8% | +54.9% |
| KITTEN | +30.7% | +18.1% |
| AERO | +18.4% | +21.5% |
| VELO | +16.2% | +30.4% |
| THE | +5.4% | +7.5% |
The ordering held and NEST kept running. NEST is also thinly traded, off a pool with roughly $245,000 of quote-side depth, so a 62.8% print describes the pool as much as the token.
We would not draw a line from these prices back to the fee numbers above. VELO is converting into AERO at a fixed ratio under the Aero merger, so it tracks that ratio rather than Velodrome's own fees. THE moved 7.5% on a venue whose take rate fell. What the prices mostly did was follow their chains.
What this means if you are locked
The repricing did reach voters. It took a week to show up, it has held for three epochs, and pool mix did as much work as volume.
The harder question is what that is worth to someone holding the position. A 45% rise in weekly payouts, a take rate at a thirteen-week high, and the best follow-through week in three years all net out to a month 3% above the one before it. Good epochs arrive and pass in a week. The position they are attached to is locked for years, and most of it cannot be unlocked at all.
So the payouts move and the position does not. For most of this inventory, what someone will pay you for the position matters more than what the next epoch pays into it.
One limit worth stating. Part of the step up is simply that ETH, BTC and the rest are worth more dollars than they were in July, so the same trades produce bigger dollar fees. We have not separated that from a genuine increase in trading. Doing it properly means taking one chain, Base, and asking whether Aerodrome grew faster than the chain underneath it. That is the next piece.
Figures are measured on the dates stated and are not updated in place; where a number is derived rather than read, the Method section says so. Last revised 17 September 2026.